Dog Insurance for Hip Dysplasia
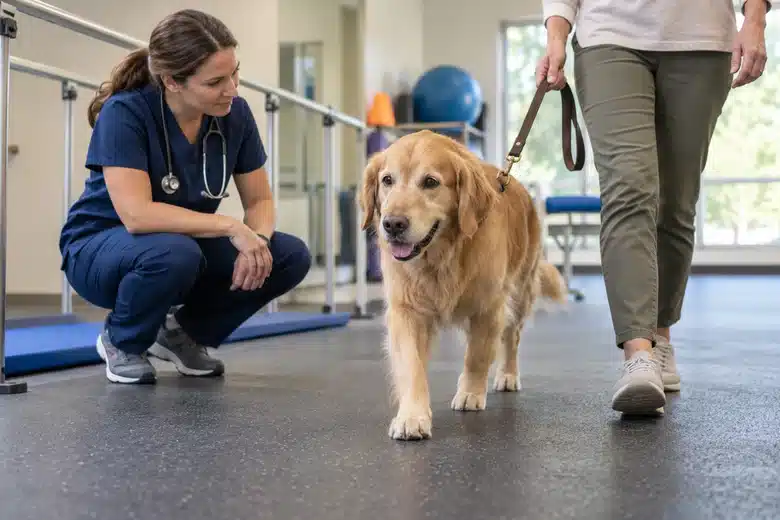
Follow a hip-dysplasia claim from the first mobility concern to separate examination, imaging, rehabilitation and surgery decisions.
What matters on this page
Use these checkpoints to frame the literal question before reading the full guide.
Dog insurance can include eligible hip-dysplasia treatment, but a hereditary-condition headline is not a promise to cover your dog’s hips. Earlier signs, the applicable waiting period, related-condition rules and selected rehabilitation or examination benefits can change the result. Start with the medical timeline and the exact policy.
The sections below show how to verify the answer and what can change it.
The limp may matter before the diagnosis does
Consider a fictional dog whose owner noticed difficulty rising before buying insurance, with hip dysplasia diagnosed afterward. A later diagnostic label does not make the earlier signs disappear. Contrast that with a dog whose first relevant signs occur after the applicable waiting period. Those timelines need separate assessment; neither can be decided from the surgery date alone.
The American College of Veterinary Surgeons describes hip dysplasia as developmental joint laxity with a strong hereditary component. Examination and imaging inform the clinical diagnosis and treatment choice. That medical account does not determine insurance eligibility. Ask the veterinary team about care promptly rather than delaying evaluation to change an insurance timeline.
Pets Best’s current coverage overview lists hip and elbow dysplasia among potentially eligible hereditary conditions, subject to pre-existing-condition and waiting-period rules. This establishes a conditional product example, not a benefit guarantee or a recommendation.
Break the estimate into insurance questions
| Invoice item | Indication/history | Relevant provision | Inclusion/exclusion evidence | Unresolved question |
|---|---|---|---|---|
| Exam | First mobility assessment or specialist consultation | Examination-fee selection | May be optional; check schedule | Is the visit fee selected for this policy? |
| Imaging | Diagnosis or surgical planning | Diagnostics plus underlying condition eligibility | No payment inferred from an X-ray order | Is it diagnostic treatment rather than screening? |
| Rehabilitation | Vet-prescribed recovery plan | Rehabilitation selection and provider rules | Separate benefit check required | Are these sessions, professional and method eligible? |
| Surgery | Procedure recommended for this dog | Illness/hereditary coverage, exclusions and remaining limit | No operation universally promised | What costs and related treatment enter the claim? |
Imaging
Rehabilitation
Surgery
Read four clauses together
Check hereditary and congenital wording, orthopedic or condition-specific waiting periods, pre-existing/related-condition definitions, and any bilateral-condition provision. A bilateral rule can matter when the other hip becomes symptomatic, but do not assume every policy has the same rule. Ask which exact clause governs both hips and preserve the answer with the form. A general illness waiting period should not be copied onto a separate orthopedic category without checking.
The Alabama-labeled Pets Best IAIC-PB10001-ILL specimen separates examination and rehabilitation as supplemental selections. Its waiting-period section distinguishes illness, injury and cruciate-ligament events. That distinction is a reason to read the actual clause, not to mislabel hip dysplasia as a cruciate event.
Ready to check current rates?
Keep policy terms, deductible, reimbursement and limits beside the quote so the comparison stays consistent.
An eligible condition still leaves an owner share
For arithmetic only, invent a $4,800 invoice: $200 examination, $600 imaging, $800 rehabilitation and $3,200 surgery. Assume the exam and rehabilitation are excluded, the other $3,800 qualifies, a $500 remaining deductible is subtracted first, and reimbursement is 80%. The illustrative payment is $2,640; the owner retains $2,160 before premiums. A different formula or an excluded underlying condition changes that result. These are not veterinary prices or a prediction of payment.
Questions to attach to the record review
Common questions
Does being a high-risk breed automatically exclude hip dysplasia?
Do not infer that result. Read the product’s eligibility, hereditary and exclusion provisions for the specific dog.
Can I buy a policy after the diagnosis?
Enrollment and reimbursement are separate. A new policy must not be assumed to pay for an already established condition; other future eligible events may still be relevant.
Ready to compare with clearer inputs?
Keep the policy terms beside the price, then continue to rates when the comparison is clear.